What we do is costly! Your support will help us dig more stories.
Yes, I'm Interested!Ignorance isn't always bliss | Don't stay foolish.
Keep informed | Read our news and analysis.
Economic instability | Central bank | Monitoring
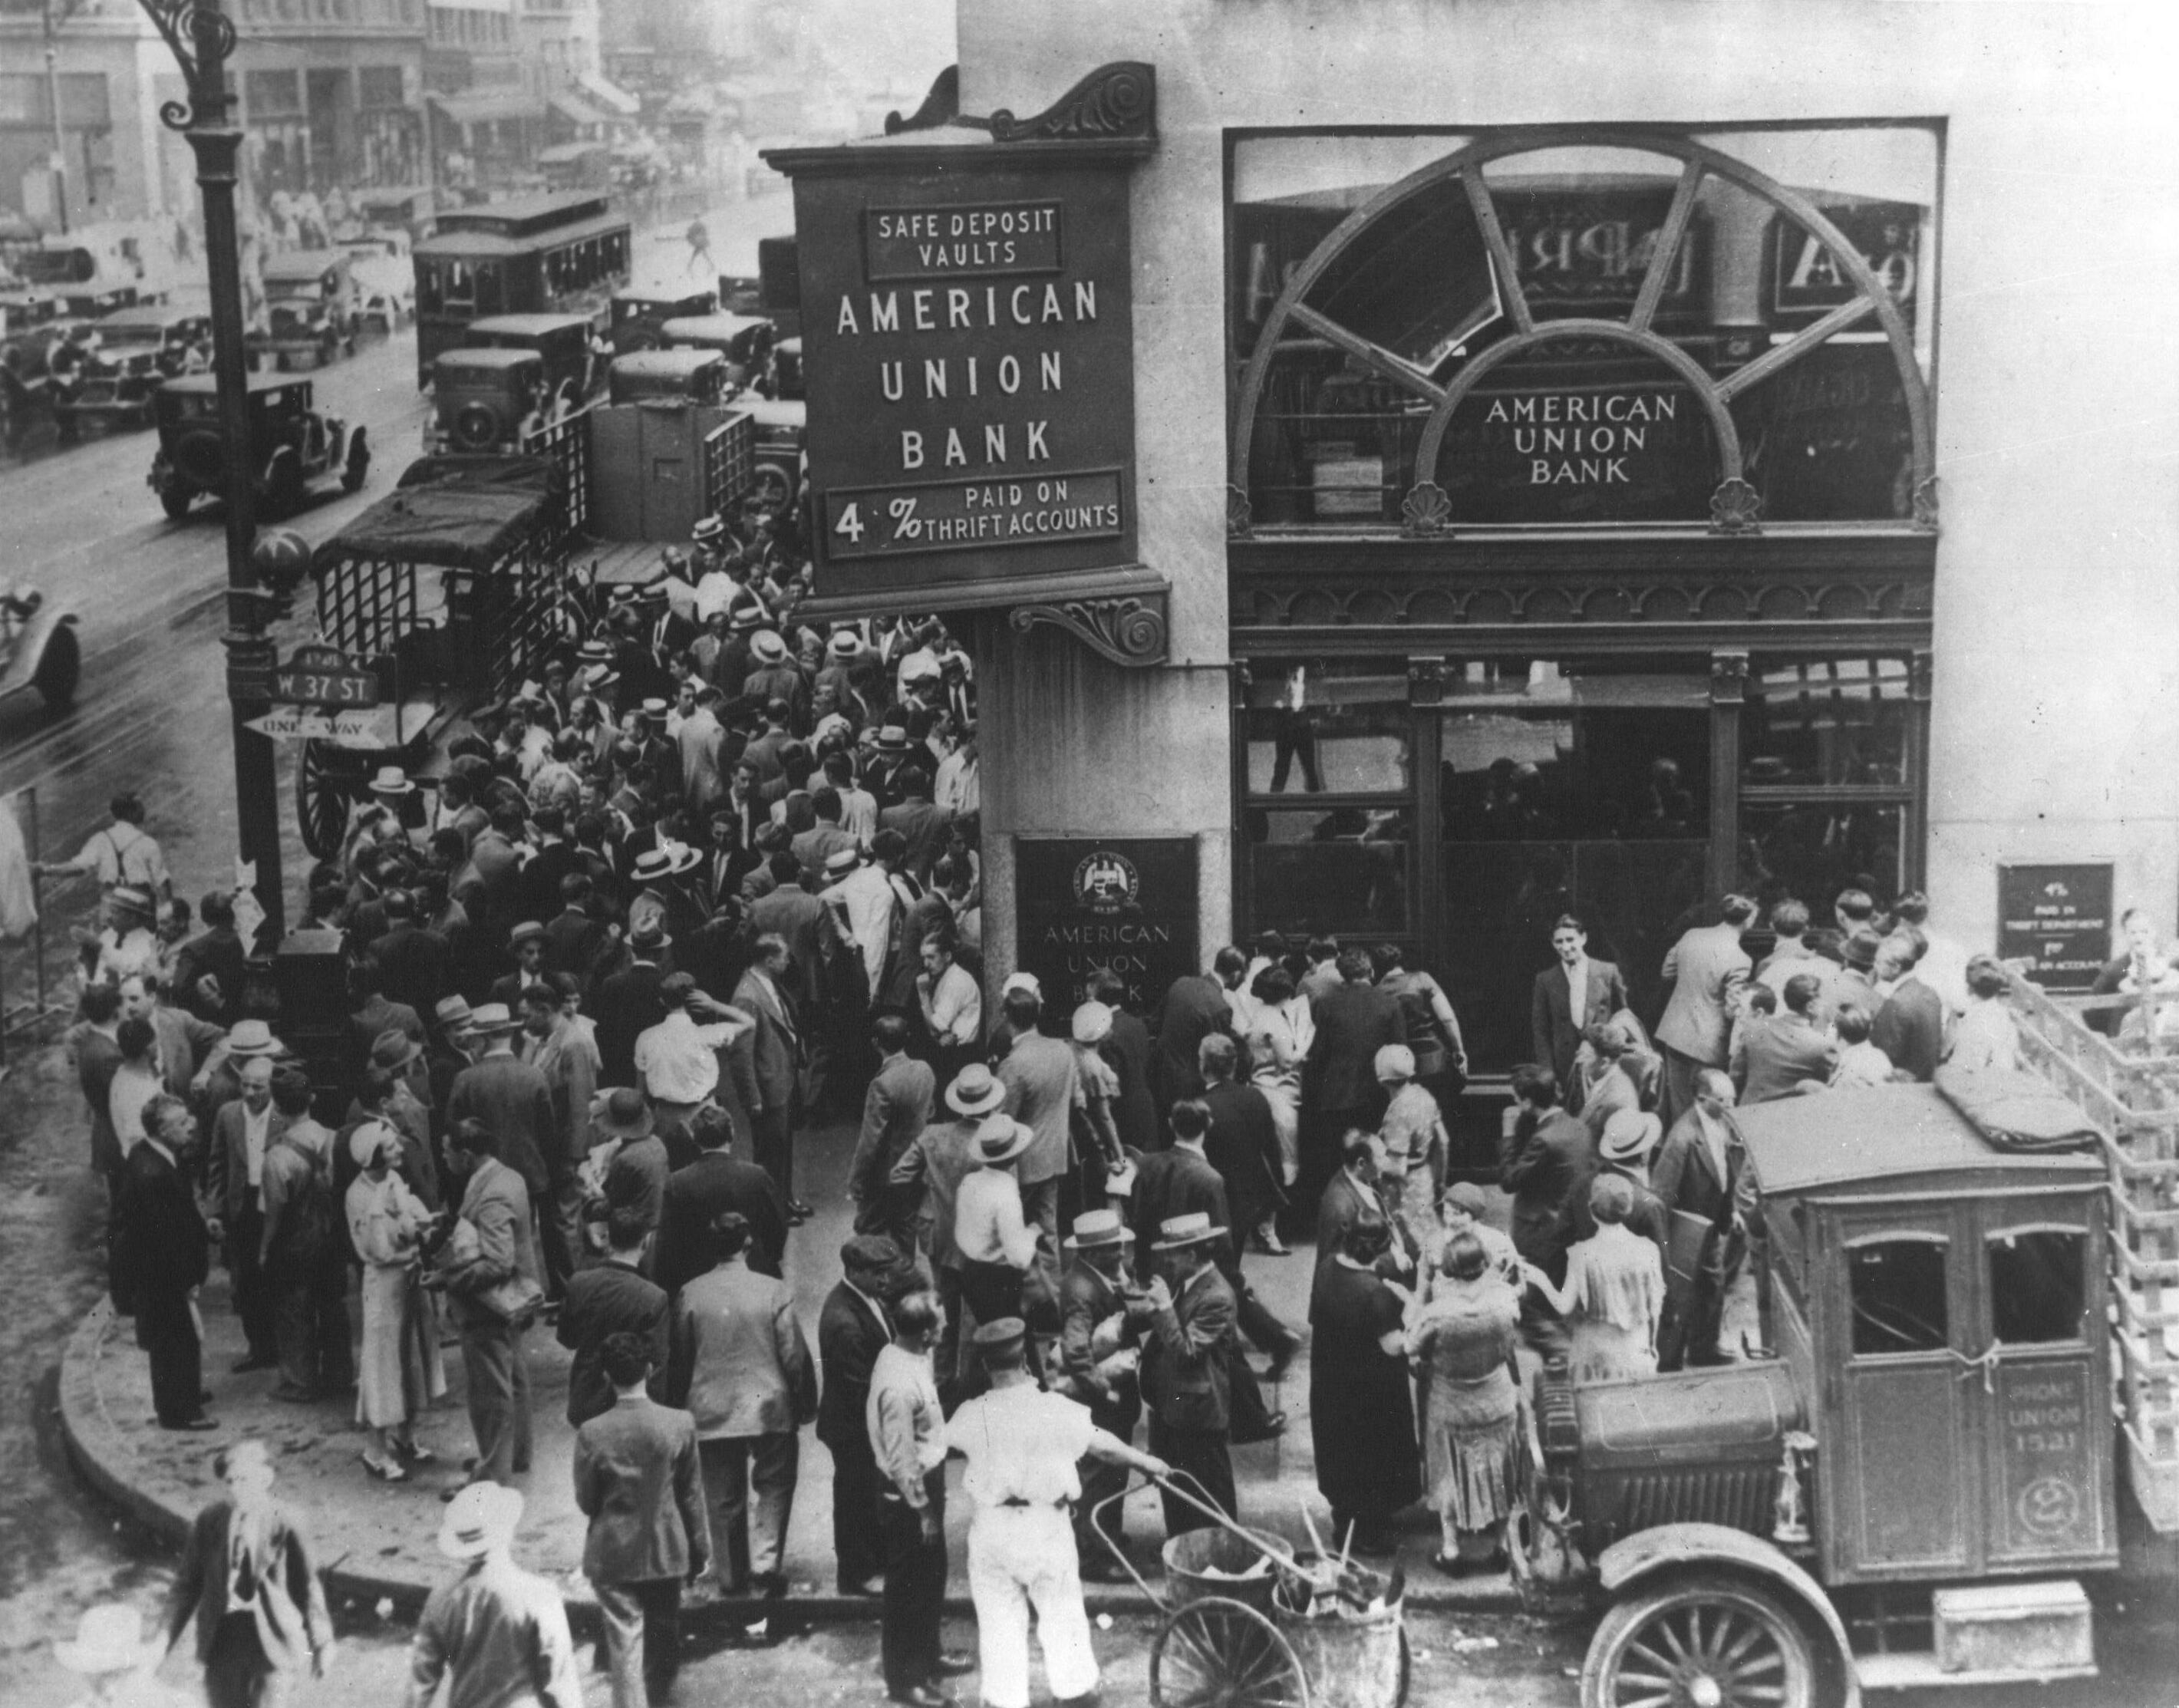
A bank run occurs when a significant group of depositors, all attempt to withdraw their money at the same time with a concern that their bank might not be able to refund it fully and promptly.
Bank runs are typically driven by fear and panic triggered by various factors — rumours about the bank’s financial health, news of other bank failures, economic instability, or a loss of confidence in the banking system as a whole.
As the banks function under the fractional reserve system, which only holds a portion of deposits in cash or in conveniently accessible forms, with the remainder being leased to borrowers or used to purchase other interest-bearing assets like government securities, even a financially stable bank may have trouble processing withdrawal requests during a bank run.
Earlier in March marked the largest bank run in history — USD 42 billion — which led to the closure of Silicon Valley Bank.
A bank must swiftly raise its cash reserves during a run to satisfy depositor demands, primarily by selling assets, often hastily and at fire-sale prices. As banks hold little capital and are highly leveraged, losses on these sales can drive a bank into insolvency.
Government and central banks play a pivotal role in preventing bank runs and maintaining financial stability. They may step in by introducing laws to monitor and oversee the banking industry, deposit insurance programs to reassure depositors, and emergency liquidity support to banks.
Read More Stories
Nepal needs to repeat to brand itself
Last year Nepal's goods exports jumped 81.8% to NRs 277.03 billion. That is...
Banking stocks gain momentum as dividend season begins
Dividend announcements by banks and financial institutions (BFIs) for fiscal year 2025/26 have...
Nepal’s challenge of building strong democratic institutions
Over the past few decades, institutional dysfunction and massive dissatisfaction with political establishments...